IG Group Shares Plunged ~22%
Online brokers: scale vs value, and the double hit to IG Group after its 2 Oct 2026 warning
I compared eight listed brokers in one currency (USD) and looked at what last week's profit warning did to IG Group. Here's how to read the tables:
1. Peer valuation
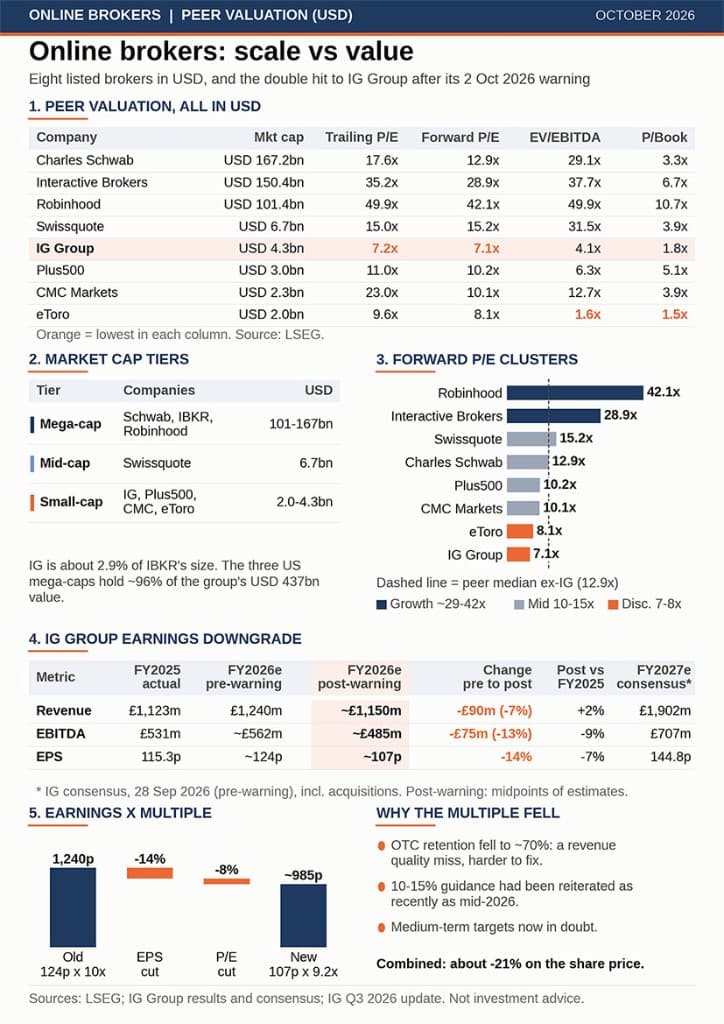
Market value and four valuation multiples for each broker. Orange marks the cheapest in each column. IG Group has the lowest trailing P/E (7.2x) and forward P/E (7.1x). eToro is cheapest on EV/EBITDA and price-to-book.
2. Market cap tiers
The group splits into three tiers. Charles Schwab, Interactive Brokers and Robinhood (USD 101-167bn) hold about 96% of the group's USD 437bn value. IG Group, at USD 4.3bn, is about 2.9% of IBKR's size.
3. Forward P/E clusters
Valuations group by business model:
- Growth premium (~29-42x): IBKR and Robinhood
- Mid-range (10-15x): Schwab, Swissquote, Plus500, CMC Markets
- Deep discount (7-8x): IG Group and eToro, both heavily exposed to OTC/CFD trading
4. IG Group's earnings downgrade
On 2 October, IG cut its 2026 revenue growth guidance from 10-15% to mid-single digits after OTC revenue retention fell to about 70% (from about 80%).
| Metric | FY2025 actual | FY2026e pre-warning | FY2026e post-warning | Change |
|---|---|---|---|---|
| Revenue | £1,123m | £1,240m | ~£1,150m | -£90m (-7%) |
| EBITDA | £531m | ~£562m | ~£485m | -£75m (-13%) |
| EPS | 115.3p | ~124p | ~107p | -14% |
FY2027 consensus (£1.9bn revenue, 144.8p EPS) predates the warning and includes recent acquisitions - expect revisions.
5. The compounding effect
The market cut both the earnings and the multiple it will pay:
124p x 10x = 1,240p → 107p x 9.2x = ~985p
EPS (-14%) x multiple (-8%) = approximately -21% on the share price.
Why the multiple fell too:
- The miss was in revenue quality, not just trading volumes
- 10-15% guidance had been reiterated as recently as mid-2026
- It raises doubts over the medium-term targets
Our take
At 7x earnings, IG is priced for more downgrades. If OTC retention recovers towards 80%, today's discount looks too wide. If it doesn't, the market is right. Is IG Group a value opportunity or a value trap?
Sources
Author: Strategyland Research Team